
About
Representation
View all Representation →Consultations- Digitisation Taskforce – Final Report
- FCA Consults on Fund Product Information and Cost Disclosure CP24/30 – ShareSoc Responds
- FRC Consults on UK Stewardship Code – ShareSoc Responds
- FCA Consultation – Modernising Redress
- HMRC Consultation – IHT on Pensions
- ShareSoc Evidence to Lords on FCA Enforcement
- ShareSoc supports FCA proposal for criminal background checks on owners and controllers of financial institutions
- UK ISA: ShareSoc submits consultation response
- FCA Consultation on Enforcement Practice & Transparency
- ShareSoc response to House of Commons Education Select Committee
- UKSA and ShareSoc Submission to Labour Party Review of Financial Services
- FCA Consultation GC23/2 Financial Promotions on Social Media
- VIEW ALL CONSULTATIONS
Education
Events
View all Events →Past Events- Oct27Equity Development – Company webinar with Ultimate Products plc
- Oct27SIGnet North Leeds / Harrogate / Skipton Group Launch Meeting
- Oct27Asset Match webinar on PISCES: what it means for liquidity in private company shares
- Oct21ShareSoc Webinar with The European Smaller Companies Trust (ESCT)
- Forums
Shepherd Neame (SHEP) – a contrarian buy in the pub sector
The ShareSoc blog provides news and informal commentary from directors, members and other contributors. Entries reflect the personal views of the authors, which do not necessarily reflect ShareSoc’s formal position. Contributors may hold shares in the companies mentioned. Nothing in this blog should be viewed as financial advice. You may submit comments on blog posts, but ShareSoc reserves the right to remove or edit inappropriate or defamatory submissions.
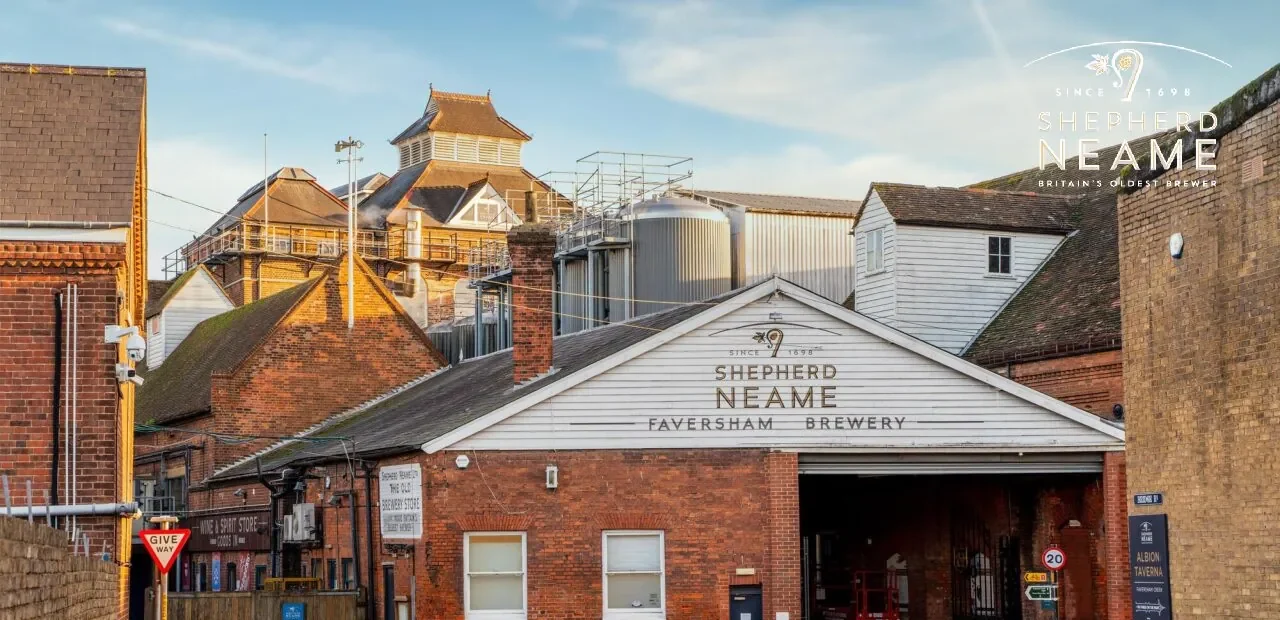
Jonathan Neame, CEO and incoming Executive Chairman of Shepherd Neame, recently presented to the SIGnet Epsom group. He gave an upbeat speech and answered questions in detail. I left feeling optimistic.
In fact, I bought shares following the meeting at £4.60. Today, (8th October 2026), the share price is still £4.60. The bid is £4.54 and the ask is £4.74.
Why the share price has dropped
The share price has fallen a long way from its 10-year high of £13 in 2017. Covid was horrid for the company. At a market cap of around £58m to £68m, it is no longer on the radar screen of fund managers. This lack of institutional interest hurts.
Inheritance tax management strategies’ changes resulting from change to Business Property Relief have also led to sales of AIM and AQUIS shares.
Both of the above factors have increased the supply of shares in the market. This has steadily pushed the price down.
What could go wrong?
It is not all plain sailing. There is plenty of negative news in the hospitality sector: we face increases in the national wage, especially for younger people; there are higher National Insurance costs and more red tape; and health trends also mean people are drinking less to cut calories and lose weight.
The pressure on brewing is specifically the fall in volume and rise in logistics costs. Total beer volumes fell 5.4% last year. Own-brand volumes dropped 9.6%.
Furthermore, limited share buybacks fail to give support to the share price. There are also heavy demands for capital expenditure; the company must constantly upgrade the estate and provide a solid return on capital employed (ROCE) on its investments.
The contrarian view
Despite the headwinds, my contrarian view is that the share price decrease is overdone. This is not a racy technology stock. This is a share where you can use the traditional methods of value investing to assess its worth; a solid, low-growth business. It is 50% owned by the family. The family is very stable but now quite dispersed. This means there is no chance of a takeover.
Shepherd Neame is well positioned in its regional niche. Its headquarters are in Faversham, Kent. It makes beautiful beer and has done for decades. There are no worries about the core product. Well-hopped beer is growing. The hotels division is growing nicely too. Most importantly, the underlying freehold-backed assets are very strong.
The valuation looks exceptionally cheap. The Net Asset Value (NAV) per share is around £12. At £4.60, the shares trade at a huge 62% discount to NAV. Edison Group research notes this is a historic 64% discount. The low valuation multiples present a stark contrast to the company’s asset strength.
The dividend yield is very attractive at around 4.7% to 5.0%. The price-to-earnings (P/E) ratio is a modest 12.3. Turnover is strong at £164 million. Recent trading momentum is also very good. Retail like-for-like sales rose 6.7% over the 13 weeks to 26 September. Investment is rightly focused on high-potential London pubs, inns, and hotels.
Shareholder perks and peers
You also get excellent shareholder benefits. You get 25% off as a gold shareholder. If you hold more than 3,000 shares, you become a black shareholder and get 30% off.
How does Shepherd Neame compare to peers like Adnams, Young & Co, and Fuller, Smith & Turner? I suggest you ask AI to do a comparison for you.
I think the business is solid. The question is whether this is a good buying opportunity.
Useful links
- Shepherd Neame – Shareholder Loyalty Scheme
- Edison Group – Strong pubs, strategic questions in brewing
- Shepherd Neame – Investor Relations
Cliff Weight, Chair of ShareSoc’s Education Committee and member of the Policy Committee. Member of SIGnet Epsom and Farnham groups.
Nothing in this article should be viewed as financial advice. Always do your own research.
DISCLOSURE: The author holds shares in SHEP.
This site uses Akismet to reduce spam. Learn how your comment data is processed.
Become a free Associate ShareSoc member
Enter your email to sign up as a free Associate ShareSoc member and receive our emails. It takes a few seconds — and on the next page you'll have the option to customise your membership.